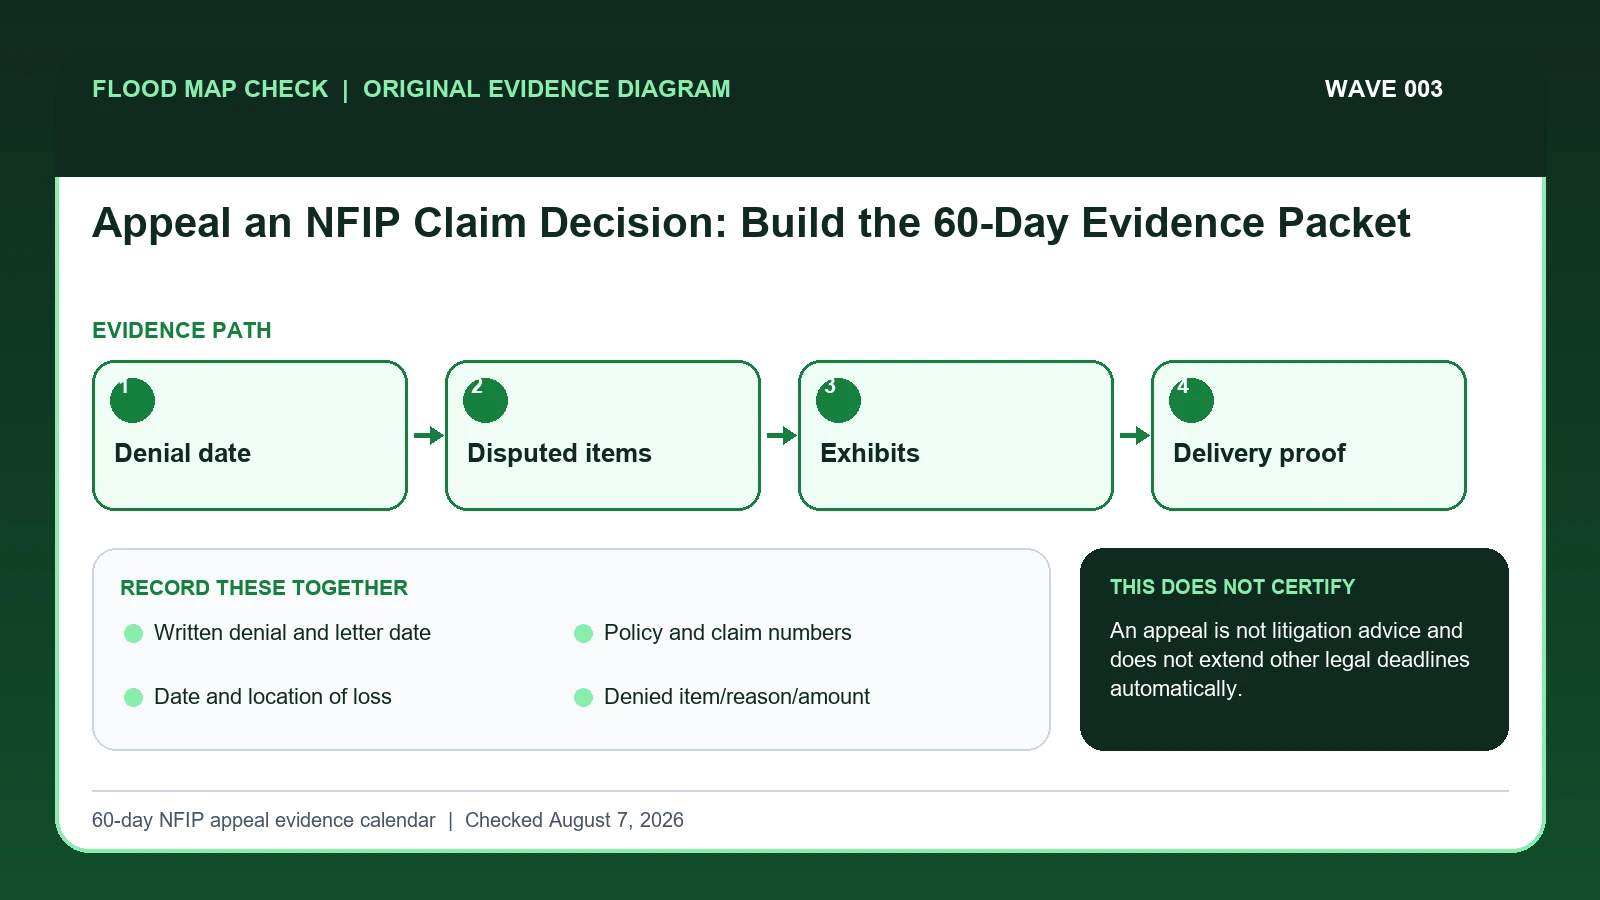
An NFIP policyholder may appeal FEMA after the insurer issues a written denial of all or part of a claim. The appeal must be submitted within 60 calendar days of the denial-letter date and should identify the policy, property, loss, disputed items, insurer decision, and supporting evidence; an appeal cannot create coverage beyond the Standard Flood Insurance Policy.
Last checked: August 7, 2026.
The denial letter starts two different clocks that should not be confused: the administrative appeal period and the separate one-year limitation for filing suit. FEMA's claims materials also explain that once a policyholder files suit, FEMA cannot consider the appeal, and appraisal choices can affect availability. This is a procedural evidence task, not a promise that the disputed amount will be paid.
Two clocks and one itemized dispute
The administrative appeal opens after an NFIP insurer denies all or part of a claim in writing. FEMA counts 60 calendar days from the date written on the denial letter. The current NFIP page explains that a mail postmark or email timestamp must fall within that period and that a deadline landing on a weekend or federal holiday extends to the next eligible day. Keep the denial date and delivery evidence in the packet's first row.
An effective appeal is itemized. For each disputed line, record the insurer's reason and amount, the policy language at issue, and the photographs, signed estimate, invoice, proof of loss, adjuster material, or correspondence that responds to that reason. If three items were denied, build three evidence rows rather than one narrative about severe damage. This makes it possible to see which factual or coverage question each exhibit is meant to answer.
The 60-day appeal period and the one-year period to file suit are separate clocks, and filing an appeal does not extend the latter. The current NFIP guidance also warns that completing appraisal prevents a FEMA appeal and that filing suit forfeits the direct FEMA appeal route. Those choices can be consequential; the article cannot select among them or provide legal advice. An appeal can correct facts or policy application, but it cannot add coverage that the Standard Flood Insurance Policy does not provide.
The denial letter, current NFIP page, and federal rule
NFIP Appeal a Claim supplies the current 60-calendar-day filing route, required denial letter and supporting documents, delivery timing, appraisal boundary, and one-year suit warning; this guide cites it for Written denial and letter date / Policy and claim numbers / Date and location of loss / Denied item/reason/amount / Supporting evidence / Policy coverage/appeal route. FEMA NFIP Claims Manual, June 2025 supplies written denial requirements, appeal timing, insurer responsibilities, and claim-process limits; this guide cites it for Written denial and letter date / Policy and claim numbers / Denied item/reason/amount / Supporting evidence / Policy coverage/appeal route. 44 CFR 62.20 supplies the federal NFIP claim-appeal rule and its procedural boundary; this guide cites it for Written denial and letter date / Policy coverage/appeal route.
The NFIP claim appeal crosswalk keeps these assignments explicit: NFIP Appeal a Claim → Written denial and letter date / Policy and claim numbers / Date and location of loss / Denied item/reason/amount / Supporting evidence / Policy coverage/appeal route; FEMA NFIP Claims Manual, June 2025 → Written denial and letter date / Policy and claim numbers / Denied item/reason/amount / Supporting evidence / Policy coverage/appeal route; 44 CFR 62.20 → Written denial and letter date / Policy coverage/appeal route. If Written denial and letter date or another named field is absent from its cited record, leave that fact unresolved and obtain it from the responsible official source instead of expanding a different citation beyond scope.
| Official record | What it actually supplies | Field used here |
|---|---|---|
| NFIP Appeal a Claim | the current 60-calendar-day filing route, required denial letter and supporting documents, delivery timing, appraisal boundary, and one-year suit warning | Written denial and letter date / Policy and claim numbers / Date and location of loss / Denied item/reason/amount / Supporting evidence / Policy coverage/appeal route |
| FEMA NFIP Claims Manual, June 2025 | written denial requirements, appeal timing, insurer responsibilities, and claim-process limits | Written denial and letter date / Policy and claim numbers / Denied item/reason/amount / Supporting evidence / Policy coverage/appeal route |
| 44 CFR 62.20 | the federal NFIP claim-appeal rule and its procedural boundary | Written denial and letter date / Policy coverage/appeal route |
Do not extend a citation beyond its mapped fields. Evidence for Written denial and letter date cannot automatically establish Policy coverage/appeal route; keep either unanswered item visible before taking the action to assemble and submit a traceable appeal within the official window.
How Written denial and letter date connects to Policy coverage/appeal route
| Field | Meaning in this check | Error it exposes | Response |
|---|---|---|---|
| Written denial and letter date | A written full or partial denial supplies the appeal gate, and its letter date starts the 60-calendar-day period | A verbal or interim discussion is not the written-denial gate, and the envelope-opened date is not the start date | Read the written decision first, then calendar the appeal from the letter date |
| Policy and claim numbers | Identify contract and loss file | Typo can misroute packet | Copy from declarations/letter |
| Date and location of loss | Tie dispute to the covered event/property | Must match insurer record | State exactly |
| Denied item/reason/amount | Defines each disputed decision | Broad complaints are hard to evaluate | Create an itemized response |
| Supporting evidence | Documents why the decision should change | Cannot add coverage excluded by policy | Cross-reference every exhibit |
| Policy coverage/appeal route | Separates a factual appeal from policy-coverage limits, appraisal, suit, or another remedy | The 60-day appeal cannot create coverage or continue after an incompatible route is chosen | Confirm the controlling policy provision and procedural route before filing |
Written denial and letter date is the starting identifier, but it is usable only when Policy and claim numbers and Date and location of loss agree. Two conflicts can break that agreement: “A verbal or interim discussion is not the written-denial gate, and the envelope-opened date is not the start date” and “Must match insurer record”. A polished screenshot cannot repair either one.
For interpretation, Policy and claim numbers answers “Identify contract and loss file”, while Supporting evidence answers “Documents why the decision should change”. They are not interchangeable. A failure in the first calls for “Copy from declarations/letter”; a failure in the second calls for “Cross-reference every exhibit”.
The final safeguard is Policy coverage/appeal route, which answers “Separates a factual appeal from policy-coverage limits, appraisal, suit, or another remedy”. Its warning condition is “The 60-day appeal cannot create coverage or continue after an incompatible route is chosen”. At that point in the NFIP claim appeal check, document the limited result or take the unresolved issue to the official decision owner.
Calendar the deadline and build exhibit rows
Verify two checkpoints before interpreting Policy coverage/appeal route: “List each denied or partially denied item, reason, and dollar amount in a dispute table”, followed by “Match each item to the policy language and factual evidence that directly responds to the reason”. If the first checkpoint fails, stop before applying the second to a possibly wrong Written denial and letter date subject or record.
- Read the entire denial letter and mark its date, policyholder, policy, claim, loss, and mailing information.
- Calculate the 60-calendar-day deadline and retain a separate note about the one-year suit limitation.
- List each denied or partially denied item, reason, and dollar amount in a dispute table.
- Match each item to the policy language and factual evidence that directly responds to the reason.
- Number exhibits and create an index covering photographs, estimates, invoices, proof of loss, and correspondence.
- Sign and send the appeal through the current official route with trackable delivery evidence.
- Keep a complete copy and seek qualified advice where litigation, appraisal, representation, or deadline conflict exists.
The file is ready for later review only after this final action: “Keep a complete copy and seek qualified advice where litigation, appraisal, representation, or deadline conflict exists”. Keep Written denial and letter date, Date and location of loss, and Policy coverage/appeal route in that record so a future update shows exactly what changed.
Three denied items become three evidence rows
If a letter denies basement finishes and part of the building estimate, make one row per disputed item. Quote the insurer's reason and dollar amount, then attach the policy provision, photographs, estimates, invoices, proof of loss, adjuster material, and correspondence that answer that reason. A general statement that the damage was severe is weaker than a dated, item-level response.
In this example, Written denial and letter date identifies the relevant record, while Date and location of loss is the fact most likely to change the interpretation. Conclude “Appeal gate is present” only when the evidence shows “Final insurer decision identifies denied item”.
For NFIP claim appeal, if the facts instead fit “Coverage not in policy”, the result changes to “Appeal cannot add coverage”. Respond by following “Focus only on supported policy interpretation/facts”. Do not substitute the more favorable conclusion from the earlier example.
Written denial, missing denial, filed suit, and uncovered loss
| Observed state | Evidence test | Limited conclusion | Next response |
|---|---|---|---|
| Written full/partial denial | Final insurer decision identifies denied item | Appeal gate is present | Prepare and send before deadline |
| No written denial yet | Only verbal or interim discussion | Appeal record is incomplete | Request the insurer's written decision |
| Suit already filed | Court action commenced | FEMA appeal generally unavailable | Use qualified legal advice |
| Coverage not in policy | Requested benefit exceeds SFIP | Appeal cannot add coverage | Focus only on supported policy interpretation/facts |
The first decision turns on “Final insurer decision identifies denied item”, while the next turns on “Only verbal or interim discussion”. Those tests lead to different conclusions—“Appeal gate is present” and “Appeal record is incomplete”—so they should remain separate in the saved record.
“Suit already filed” calls for “Use qualified legal advice”, but “Coverage not in policy” calls for “Focus only on supported policy interpretation/facts”. Reporting the Suit already filed and Coverage not in policy differences is more accurate than forcing both conditions into one generalized warning.
Appraisal, suit, missing denial language, and delivery proof
- Avoid counting from receipt instead of letter date. Recheck Written denial and letter date. The mapped warning is “A verbal or interim discussion is not the written-denial gate, and the envelope-opened date is not the start date”; the corresponding response is “Read the written decision first, then calendar the appeal from the letter date”.
- Avoid appealing before written denial. Recheck Written denial and letter date. The mapped warning is “A verbal or interim discussion is not the written-denial gate, and the envelope-opened date is not the start date”; the corresponding response is “Read the written decision first, then calendar the appeal from the letter date”.
- Avoid mixing the 60-day and one-year clocks. Recheck Written denial and letter date / Policy coverage/appeal route. The mapped warning is “A verbal or interim discussion is not the written-denial gate, and the envelope-opened date is not the start date; The 60-day appeal cannot create coverage or continue after an incompatible route is chosen”; the corresponding response is “Read the written decision first, then calendar the appeal from the letter date; Confirm the controlling policy provision and procedural route before filing”.
- Avoid asking the appeal to add unavailable coverage. Recheck Policy coverage/appeal route. The mapped warning is “The 60-day appeal cannot create coverage or continue after an incompatible route is chosen”; the corresponding response is “Confirm the controlling policy provision and procedural route before filing”.
Check Written denial and letter date when the risk is “counting from receipt instead of letter date”, because the mapped warning is “A verbal or interim discussion is not the written-denial gate, and the envelope-opened date is not the start date”. Check Written denial and letter date separately for “appealing before written denial” and use “Read the written decision first, then calendar the appeal from the letter date” as the recovery step.
Two field-specific corrections are required. For “mixing the 60-day and one-year clocks”, follow “Read the written decision first, then calendar the appeal from the letter date; Confirm the controlling policy provision and procedural route before filing”. For “asking the appeal to add unavailable coverage”, follow “Confirm the controlling policy provision and procedural route before filing”. Keeping Written denial and letter date / Policy coverage/appeal route separate from Policy coverage/appeal route prevents one repaired field from hiding the other error.
What this 60-day NFIP appeal evidence calendar cannot decide
Scope: United States NFIP and lender-required flood insurance workflows. Limitation: An appeal is not litigation advice and does not extend other legal deadlines automatically.
The value of the 60-day NFIP appeal evidence calendar is traceability: it places Written denial and letter date, Date and location of loss, and Policy coverage/appeal route beside their sources. Authority to decide the underlying Written denial and letter date remains with the organization named in the official record.
Keep proof-of-loss and policy questions beside the appeal
- Consult Standard Flood Hazard Determination Form Guide after Written denial and letter date has been matched to the correct subject and date.
- Consult Newly Mapped Flood Zone Insurance for the distinct issue revealed by Date and location of loss.
- Consult NFIP Proof Of Loss Flood Claim when Policy coverage/appeal route changes the next official step beyond the action to assemble and submit a traceable appeal within the official window.
Use this guide to assemble and submit a traceable appeal within the official window. The linked guides address separate questions raised by Written denial and letter date, Date and location of loss, or Policy coverage/appeal route.
Before sending an NFIP appeal to FEMA
Does Written denial and letter date settle the question by itself?
No. Written denial and letter date answers “A written full or partial denial supplies the appeal gate, and its letter date starts the 60-calendar-day period”, but it can fail when “A verbal or interim discussion is not the written-denial gate, and the envelope-opened date is not the start date”. Pair it with Policy and claim numbers, Date and location of loss, and the checked date.
What if the evidence shows Coverage not in policy?
Confirm the stated evidence test: “Requested benefit exceeds SFIP”. The limited conclusion is “Appeal cannot add coverage”. The documented response is “Focus only on supported policy interpretation/facts”; a more favorable branch should not be substituted.
When should Policy coverage/appeal route be checked again?
Calculate the appeal deadline from the written denial and verify delivery requirements before sending the packet. Recheck immediately if the insurer corrects the denial, supplies missing reasons, changes an itemized amount, or litigation begins, because those facts can change the available route.
Appeal an NFIP Claim Decision: Build the 60-Day Evidence Packet is independent public-record guidance for the limited action to assemble and submit a traceable appeal within the official window. The cited government records retain authority over Written denial and letter date and Policy coverage/appeal route. Last checked: August 7, 2026.